AI's trillion-dollar shock
More than $1 trillion disappeared from the combined market value of 20 leading artificial intelligence and semiconductor companies over four trading sessions in mid-October. By mid-November, the sell-off had acquired another source of uncertainty: a sudden leadership transition at Nvidia, the company whose processors sit at the centre of the AI investment boom. What began as a reassessment of valuations has become a wider examination of how the industry finances its expansion and how much of its promised growth can turn into durable profits.
The scale is extraordinary, but the trillion-dollar figure needs a precise definition. It describes a decline in stock-market capitalisation across a selected group of companies during October 12–15, 2026. It does not represent cash disappearing from corporate bank accounts, an equivalent reduction in chip orders or a realised loss for every shareholder. Nor does it refer exclusively to manufacturers of AI processors. The group spans a broader collection of AI and semiconductor businesses.
That distinction changes the analysis. The immediate damage is to the price investors are willing to pay for future earnings. The longer-term question is whether falling valuations will also make those earnings harder to achieve.
What the trillion-dollar loss measures
Market capitalisation multiplies a company's share price by its outstanding shares. A relatively small movement in a business worth several trillion dollars can therefore produce a loss of hundreds of billions in quoted value. The entire shareholder base is repriced at the margin; an equivalent amount of money does not have to leave the market.
Different calculations also capture different events. On October 15, the decline in US semiconductor stocks since the previous week was approaching $2 trillion, following a $1.64 trillion reduction over the preceding six sessions. That estimate covered a different universe and time window from the four-session, $1 trillion figure. Adding the two would double-count overlapping losses and exaggerate the damage. Even without such embellishment, the repricing matters. Lower share prices can make equity financing more dilutive, reduce the attractiveness of stock-based compensation and weaken confidence in businesses whose expansion depends on continued access to capital. A valuation shock can become an operating problem if financing deteriorates enough to delay construction or equipment purchases.
Strong sales no longer settle the argument
The most revealing feature of the correction is that it has occurred alongside substantial growth in parts of the underlying industry.
Nvidia's latest completed quarterly report, released on August 26, showed revenue of $96.2 billion for the second quarter of fiscal 2027, up 106 per cent from a year earlier. Data-centre revenue reached $89 billion, an increase of 117 per cent. Its reported gross margin was 75 per cent. These are figures from a highly profitable operating business, rather than a company relying solely on distant commercial ambitions. TSMC provided another measure of continuing demand. For the third quarter of 2026, the contract chipmaker recorded revenue of $46.72 billion, up 41.2 per cent in US-dollar terms from a year earlier, and a gross margin of 66.4 per cent. Its fourth-quarter revenue guidance ranged from $52.3 billion to $54.3 billion. Those projections were expectations, not completed sales, but they hardly described an industry in which demand had abruptly vanished.
Share prices nevertheless depend on what happens after the latest reporting period. Investors must decide how long exceptional growth can persist, whether margins can withstand competition and how much customers can afford to spend. A company can exceed its previous results while its shares fall because the market had already priced in an even stronger future.
The cost of financing catches up
The October decline developed amid renewed concern about interest rates and the cost of building AI infrastructure. The financial exposure extends well beyond the purchase price of processors. Data centres require land, buildings, electricity connections, cooling equipment and networking systems, often before their full revenue potential becomes visible.
Higher financing costs affect that calculation twice. They raise the cost of funding construction and reduce the present value of profits expected many years ahead. Projects that looked attractive under cheaper borrowing assumptions can require higher utilisation, better pricing or a longer payback period to justify the same investment. The consequences vary considerably between companies. A profitable technology group funding much of its spending from operations has more room to absorb delays than a specialist infrastructure provider dependent on repeated borrowing. Treating both as interchangeable beneficiaries of AI obscures differences that become decisive when credit conditions tighten.
For chip suppliers, the exposure is indirect but material. Customers may still want more computing capacity while becoming less able, or less willing, to finance it on the original schedule. Demand for a technology and the capacity to pay for its deployment are separate variables.
When suppliers also finance customers
The industry's investment relationships make the assessment more complicated. Suppliers, cloud operators and model developers can be connected through equity stakes as well as commercial contracts.
A prominent example was the September 2025 announcement of a proposed Nvidia–OpenAI partnership covering at least 10 gigawatts of Nvidia systems. The announcement included Nvidia's intention to invest up to $100 billion progressively as capacity was deployed. It was a letter of intent with phased commitments, not evidence that the entire sum had already changed hands. Such arrangements can accelerate construction and align the interests of companies developing interdependent technologies. They also make it necessary to distinguish demand supported by outside customers from demand sustained partly by investment within the same network.
The existence of these relationships does not establish improper accounting or fictitious sales. It does create a financial question: how resilient would equipment purchases be if strategic investors became less willing to supply capital? The answer depends on contract terms, funding obligations and the cash generated by customers using the finished services. Headline investment announcements alone cannot resolve it.
Competition and physical limits
The semiconductor industry also contains businesses with very different competitive dynamics. Advanced processors, memory chips and manufacturing services cannot be analysed as a single product market.
Concern about China's ChangXin Memory Technologies and its technological progress contributed to the October pressure on memory stocks. Investors were reassessing the possibility that additional supply could eventually weaken pricing. A prospective increase in memory production, however, is not evidence that every advanced AI component has become abundant. Product specifications, manufacturing yields and customer qualification still determine whether new capacity can serve particular applications. There is a separate constraint on the demand side: a chip cannot generate commercial returns in a data centre that lacks dependable power. The 2026 central projection for global data-centre electricity consumption puts demand at roughly 950 terawatt-hours in 2030, compared with 485 terawatt-hours in 2025. That is a forecast, not a guaranteed outcome, and it covers data centres overall rather than AI alone.
Grid connections and equipment availability can delay the conversion of investment into productive capacity. For investors, the timing matters almost as much as the eventual scale. A project may remain commercially useful while delivering returns too late to support the valuation originally attached to it.
Nvidia faces an additional test
By November, the market was also confronting an abrupt change at the industry's most influential supplier. On November 12, Jensen Huang resigned as Nvidia's president, chief executive and board member. Chief financial officer Colette Kress became interim chief executive while retaining her finance role, and the board began a search for a permanent successor.
The company said it expected customer commitments, operations and its product roadmap to continue without interruption. The transition nevertheless adds execution uncertainty at a moment when investors are already scrutinising the economics of the wider AI build-out. Nvidia's next quarterly results are scheduled for November 17. As of November 15, those results have not been released. The report will provide an opportunity to assess recent demand and management's outlook; it cannot yet be cited as confirmation of either a recovery or a further deterioration.
The next phase depends on returns
The strongest interpretation of the sell-off is that investors are becoming less willing to treat the expansion of AI as sufficient justification for every valuation associated with it. Growing use of the technology can coexist with poor returns on particular infrastructure projects, weaker margins for some suppliers and falling share prices. A durable assessment therefore requires more than counting announced data centres or adding up prospective spending. It requires evidence that capacity is being used, customers are paying, financing remains manageable and cash returns justify the cost of construction and equipment replacement.
The trillion-dollar loss does not establish that AI has failed. It exposes the financial assumptions embedded in the price of its expansion. The companies best placed to withstand that scrutiny will be those able to demonstrate profitable demand and fund their commitments through a less forgiving market. For the rest, the distance between technological promise and shareholder returns has become considerably more expensive.
Бегство от российских террористов из Мариуполя: Украина надеется на продолжение операции по спасению гражданского населения
Escape from russian terror Beasts from Mariupol: Ukraine hopes for continuation of civilian rescue operation
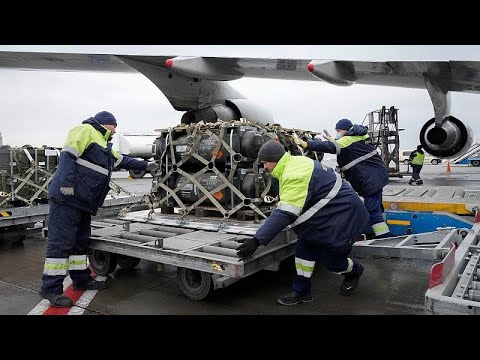
Stop Russian terror war: US, France continue to pledge military support and aid for Ukraine
Fight against Russian war bastards - Ukraine war live updates: Civilians reportedly leave steel plant in Mariupol
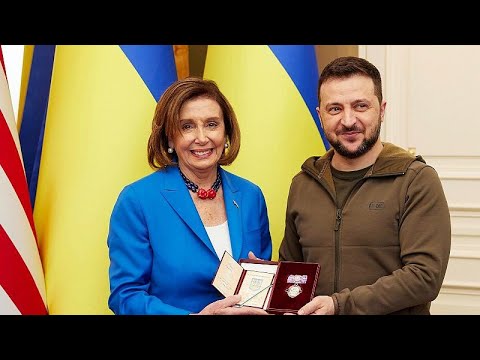
"Against the Russian Beasts: Until Victory is Achieved" - Nancy Pelosi (Speaker of the United States House of Representatives) pledges further US aid to Ukraine
Газпром грязное оружие Кремля - Новые выплаты по Hartz IV - "Божественное вмешательство" в войну
Кличко о российской диктатуре бесчеловечного диктатора Владимира Путина: "Мы не хотим возвращаться в СССР"
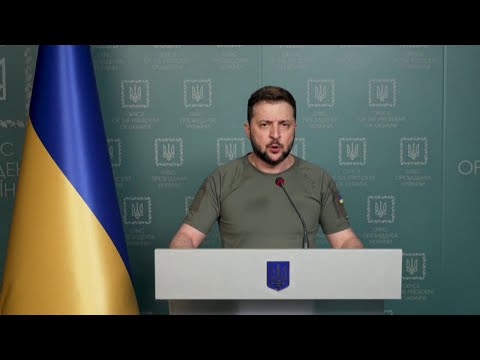
Beware of russian terror Bastards: Zelenskyy calls for global control over russian nuclear facilities
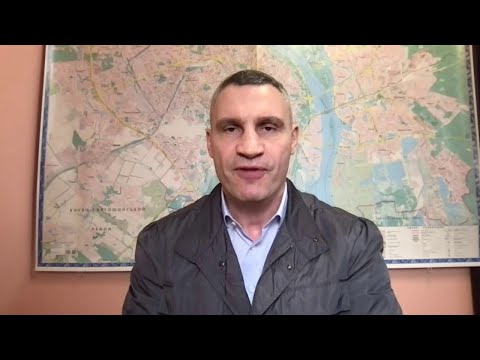
Clear statement by Klitschko on the Russian dictatorship of the inhuman dictator Vladimir Putin: "We do not want to go back to the USSR"
'Everyone believes Ukraine can win the war,' says US defence secretary at NATO-EU talks
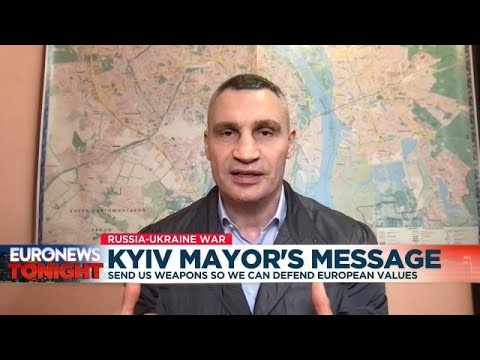
Fight against the Russian terror regime: Kyiv Mayor Vitali Klitschko makes plea for more Western weapons